The Ukrainian feed barley market enters October with a noticeable surplus of supply. Against the backdrop of weaker exports and restrained demand from external buyers, port prices have declined, and sellers are increasingly paying closer attention to logistics and storage costs.
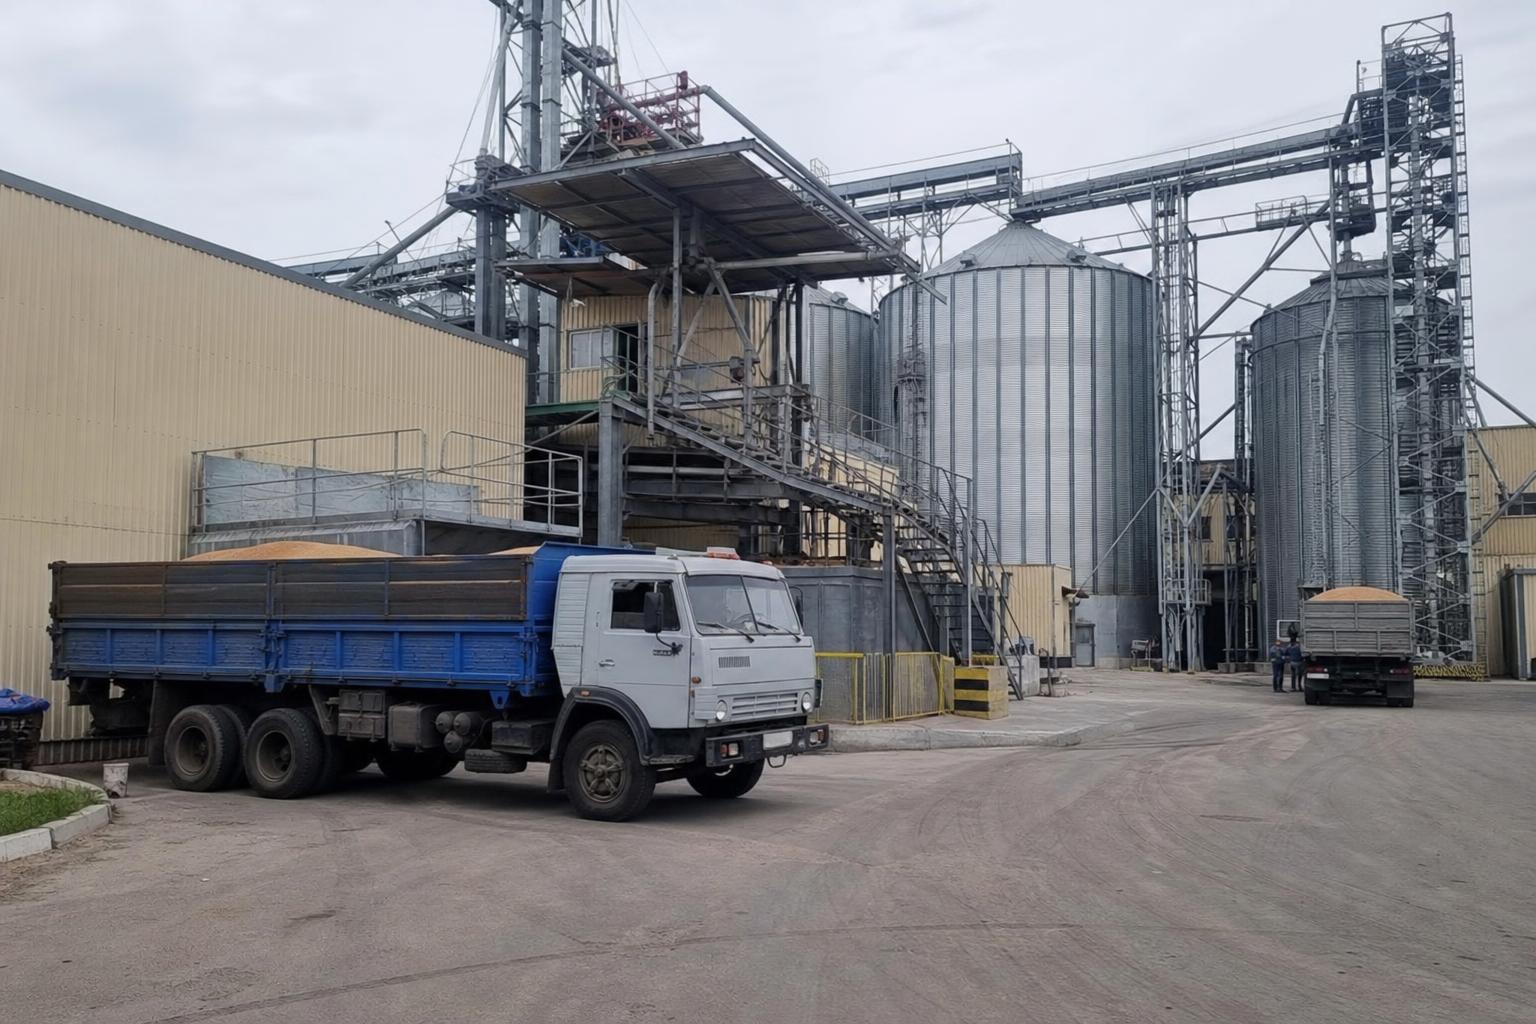
For elevators, traders, and farms, this means more intense competition for buyers. Meanwhile, for processors and feed grain purchasers, the current market conditions open opportunities to selectively form batches based on quality and delivery basis.
Barley stocks significantly higher than last year
As of September 1, barley stocks in Ukraine were estimated at 2.5 million tons. This is 83.7% higher than the previous year, and this factor remains one of the main sources of pressure on the domestic market.
The total crop harvest amounted to 6.58 million tons. With such volumes, active export or stable domestic demand is needed to quickly unload elevator stocks. Currently, neither of these factors provides sufficient momentum for price recovery.
Exports are slower than market expectations
Since the start of the season, Ukraine has exported approximately 440,000 tons of barley. In September, shipments were around 60,000 tons, confirming cautious activity from external buyers.
Global demand remains weak from North African and Middle Eastern countries. An additional market signal was Jordan’s cancellation of a tender to purchase 120,000 tons of barley.
The competitive environment is also challenging. The European Commission has increased its forecast for EU barley production to 53.6 million tons, with end stocks estimated at 2.5 million tons. This limits the short-term potential for a sharp increase in demand for Ukrainian supplies.
Prices in ports are declining
As of October 1, purchase prices for feed barley in Danube ports decreased by $2–5/ton and mostly ranged between $140–150/ton CPT port.
In hryvnias, port prices mostly ranged from 6,800 to 7,800 UAH/ton CPT port. Compared to early September, this is lower by 200–800 UAH/ton.
On the DAP-Mostyska basis, demand prices were mostly quoted at $138–142/ton. The average decrease in this segment was approximately $2/ton.
Logistics remains a key margin element
In regional grain trading, the Black Sea remains a critically important route. Alternative routes for regional exporters, including through the Baltic, Caspian, and Far East, have limited capacity and higher costs.
Market estimates suggest that alternative Russian ports handled about 1.3 million tons of grains and oilseeds from July to September, while main Black Sea facilities can process around 12 million tons in the same period. This demonstrates that logistical constraints in the Black Sea region continue to influence the entire grain trade.
For Ukrainian sellers, this means that the delivery basis can be just as important as the price itself. The difference between port, western transit, elevator, and farm directly impacts the final margin.
Key conclusions for sellers and buyers
- For barley sellers: compare not only the price but also acceptance conditions, moisture content, foreign matter, shipment schedule, and transportation costs to the basis.
- For elevators: work with transparent batches by quality, as surplus supply increases buyer requirements for documentation and grain condition.
- For feed grain buyers: may have a stronger bargaining position, especially if willing to pick up batches from regions with high stocks.
- For traders: closely monitor tender activity from importers, as the recovery of external demand could change the market tone.
What this means for the market
The barley market in Ukraine currently remains a buyer’s market: stocks are sufficient, export pace is weak, and port prices are declining. For AgroPost participants, the practical focus is on quickly comparing offers, fixing batch quality, and calculating full logistics to a specific basis, rather than relying solely on nominal price per ton.
Comments
No comments yetNo comments yet - be the first.